
KBRA Assigns AA Rating to MTA Transportation Revenue Refunding Green Bonds
KBRA has assigned a long-term rating of AA to the Metropolitan Transportation Authority’s (MTA) New York Transportation Revenue Refunding Green Bonds, Series 2026A, which are Climate Bond Certified. At the same time, KBRA affirmed its AA long-term rating on the authority’s outstanding Transportation Revenue Bonds. The rating outlook remains Stable.
The latest rating action reflects KBRA’s assessment of the MTA’s revenue position, liquidity, operating flexibility, financial obligations and the essential role its transportation network plays across New York and the surrounding metropolitan region.
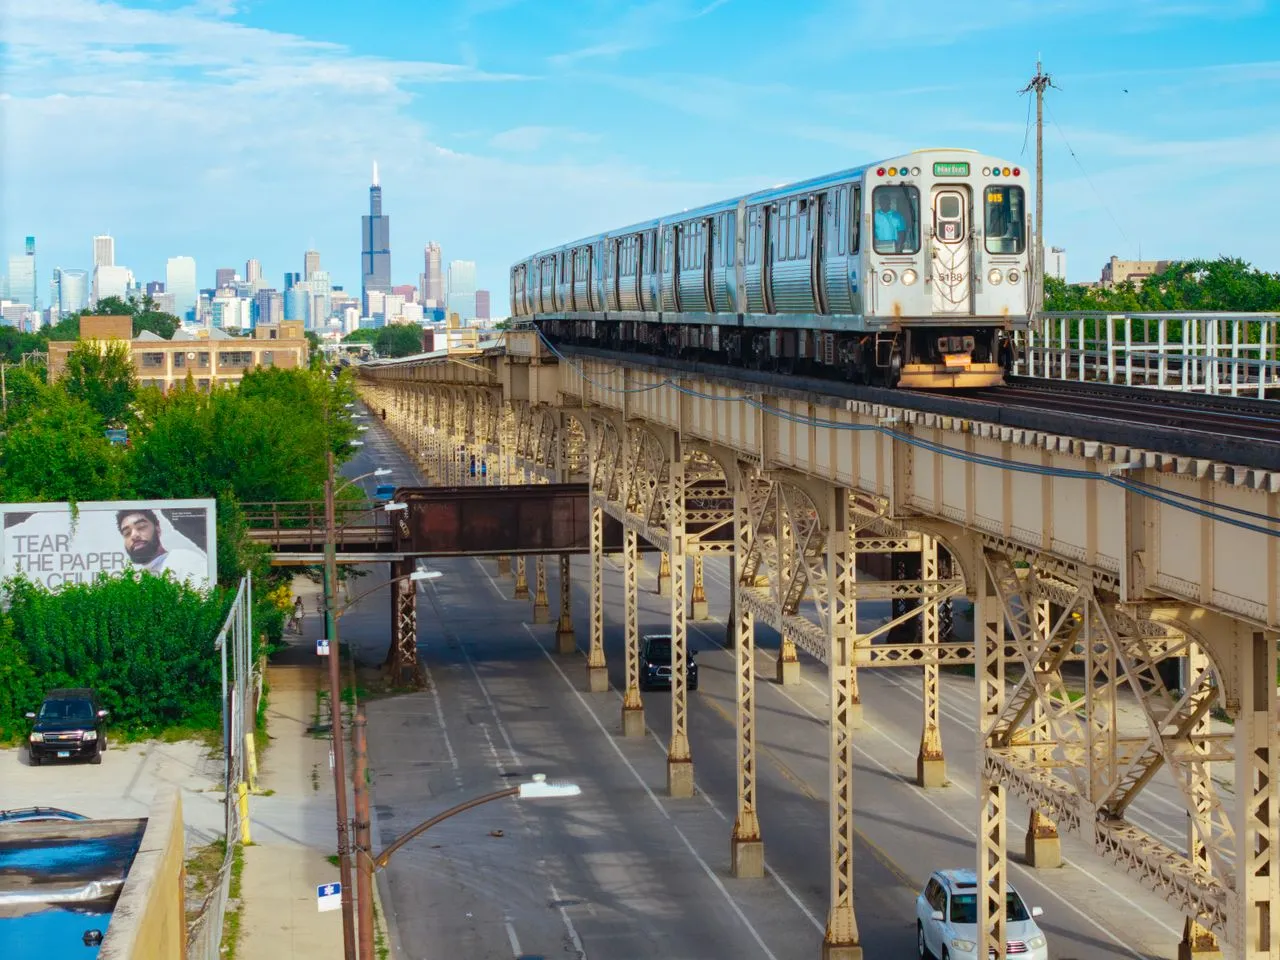
The MTA operates one of the largest and most important public transportation systems in the United States. Its transportation assets provide mobility for more than 15 million people, supporting daily travel throughout New York City and the broader metropolitan area. Because of the scale and importance of the network, the authority’s financial condition and ability to maintain its infrastructure remain closely connected to the economic activity of the region.
Strong Revenue Pledge Supports Credit Profile
One of the key factors supporting KBRA’s AA rating is the strength of the gross revenue pledge securing the Transportation Revenue Bonds. According to KBRA, pledged transportation revenues provide strong coverage of annual debt service, helping support the authority’s ability to meet its debt obligations.The MTA also benefits from sound liquidity and reserves. These financial resources provide the authority with additional operating flexibility and can help it manage periods of financial pressure or unexpected changes in revenues and expenditures.
Strong debt service coverage is particularly important for the MTA because the authority operates a large and complex transportation system requiring substantial ongoing investment. Maintaining sufficient pledged revenues to cover debt obligations gives the authority a stronger financial foundation as it addresses its long-term capital requirements.
KBRA’s assessment also recognizes the importance of the MTA’s transportation assets to the regional economy. Millions of people rely on the authority’s subway, commuter rail and other transportation services for access to employment, businesses and other economic activities. The scale of the system means that reliable transportation infrastructure is an important component of the economic functioning of New York City and its surrounding communities.
Essential Transportation Network
The MTA’s transportation infrastructure serves a population exceeding 15 million people, making the authority a critical component of regional mobility.Its transportation network supports commuters, residents, businesses and visitors throughout the metropolitan area. The continued operation and maintenance of this infrastructure therefore have implications beyond the authority itself, including the broader economic performance of the region.
This essential-service characteristic is an important element of KBRA’s credit assessment. Transportation systems of this scale require significant and continuous spending on maintenance, rehabilitation, modernization and expansion. The MTA must balance these capital requirements with operating costs, debt service and other financial obligations.The Series 2026A bonds are also identified as Climate Bond Certified, reflecting their designation within a framework associated with climate-related financing. The bonds form part of the authority’s broader financing activity while the MTA continues to address infrastructure needs across its extensive transportation system.
Aging Infrastructure Remains a Long-Term Challenge
Despite the strengths supporting the rating, KBRA identifies several challenges facing the MTA.One of the major issues is the age of portions of the authority’s infrastructure. Maintaining an extensive transportation network requires sustained investment to keep assets in a state of good repair. Aging infrastructure can increase maintenance requirements and create additional pressure on capital budgets.
Climate change resilience is another long-term consideration. Transportation infrastructure must increasingly account for environmental risks and the need to improve resilience against climate-related impacts. Addressing these requirements can involve substantial capital expenditures over an extended period.At the same time, changing ridership patterns represent another challenge for the MTA. Transportation demand can evolve because of changes in commuting habits, economic conditions and broader travel behavior. Such changes can influence fare-related and other transportation revenues while the authority continues to carry significant fixed costs.These factors make long-term financial planning particularly important for the MTA.
Rising Non-Discretionary Costs Add Pressure
KBRA also highlights the potential impact of increasing non-discretionary expenditures on the authority’s finances.Although the MTA has benefited from favorable revenue performance and continued efficiency efforts, significant financial gaps remain. Growth in expenses that are difficult to reduce or defer can increase pressure on the authority’s operating budget.
Labor-related obligations are among the areas contributing to the MTA’s fixed-cost burden. Other expenses identified by KBRA include health and other post-employment benefits, liability and claims costs, workers’ compensation, energy expenses and paratransit costs.These expenditures can limit the authority’s ability to quickly adjust its operating structure when financial conditions change. As a result, maintaining structurally balanced operations remains an important consideration for the authority’s long-term credit position.
High Fixed Costs Remain a Credit Consideration
The MTA has an exceptionally high fixed-cost burden. Contractually required labor-related obligations and debt service account for a significant portion of the authority’s financial commitments.High fixed costs can make it more difficult for a transportation agency to respond to revenue volatility or unexpected expenditure increases. While strong pledged revenue coverage and available liquidity provide important support, the authority must continue managing its operating expenses and long-term obligations carefully.
KBRA considers this fixed-cost structure an impediment to achieving ongoing structurally balanced operations. Addressing these pressures will remain important as the MTA proceeds with its capital program and maintains its transportation network.The combination of aging infrastructure, significant capital requirements, fixed operating costs and evolving ridership patterns creates a complex financial environment for the authority.
Capital Program Remains Important
The delivery of the MTA’s capital program is another significant consideration in KBRA’s assessment.The authority requires substantial investment to maintain and modernize its transportation assets. Critical projects, including state-of-good-repair initiatives, are necessary to preserve the reliability and condition of the system.
KBRA indicates that successful delivery of critical capital program elements, while maintaining strong debt service coverage from pledged transportation revenues, could support positive rating momentum.Capital investment is particularly important given the age and scale of the MTA’s infrastructure. Completing projects effectively can help address deferred maintenance, improve system resilience and support the long-term functionality of the transportation network.
However, major capital requirements must be balanced against the authority’s existing financial obligations. Sustaining adequate resources for debt service while funding necessary infrastructure improvements will remain an important part of the MTA’s financial management.
Conditions That Could Affect the Rating
KBRA has outlined several factors that could influence the MTA’s credit rating in the future.For potential upward rating movement, KBRA points to the successful delivery of critical components of the capital program, particularly projects designed to maintain the system in a state of good repair. Continued strong coverage of debt service through pledged Transportation Revenues would also be important.
On the other hand, continued structural operating imbalances could create downward pressure on the rating. KBRA specifically identifies expenses associated with labor, health and other post-employment benefits, liabilities and claims, workers’ compensation, energy and paratransit as areas that could contribute to financial pressure.A material decline in pledged revenue coverage could also affect the credit profile. Such deterioration could result from sustained operating pressures, a significant increase in leverage or a reduction in resources supporting the Transportation Revenue Bond credit.These considerations highlight the importance of both revenue performance and expenditure management for the MTA’s long-term financial position.
KBRA has assigned a Stable Outlook
The AA rating. The outlook reflects the rating agency’s current assessment of the balance between the MTA’s financial strengths and its long-term challenges.The authority benefits from strong transportation revenue coverage, sound liquidity and the essential nature of its transportation assets. At the same time, it faces significant infrastructure investment needs, high fixed costs, changing ridership patterns and pressure from non-discretionary expenditures.
Maintaining financial stability will therefore depend on the MTA’s ability to preserve sufficient revenue coverage while addressing its capital and operating requirements.The Series 2026A Transportation Revenue Refunding Green Bonds represent another financing activity for the authority as it manages its long-term transportation infrastructure and financial obligations. The Climate Bond Certified designation also places the bonds within the broader context of climate-related financing.
Overall, KBRA’s AA rating reflects its assessment of the MTA’s strong revenue pledge and financial resources, balanced against the substantial operating and capital challenges associated with managing one of the nation’s largest public transportation systems.The rating will continue to be influenced by the authority’s ability to maintain debt service coverage, manage structural operating pressures, deliver key capital projects and preserve the resources supporting its Transportation Revenue Bonds.
KBRA’s methodology for the rating includes its Public Finance: U.S. Public Toll Roads, Bridges & Tunnels Revenue Bond Rating Methodology. Additional information concerning the rating, disclosures, methodologies and relevant supporting documents is available through KBRA’s official ratings and disclosure resources.
About KBRA
Kroll Bond Rating Agency, LLC (KBRA), one of the major credit rating agencies (CRA), is a full-service CRA registered with the U.S. Securities and Exchange Commission as an NRSRO. Kroll Bond Rating Agency Europe Limited is registered as a CRA with the European Securities and Markets Authority. Kroll Bond Rating Agency UK Limited is registered as a CRA with the UK Financial Conduct Authority. In addition, KBRA is designated as a Designated Rating Organization (DRO) by the Ontario Securities Commission for issuers of asset-backed securities to file a short form prospectus or shelf prospectus. KBRA is also recognized as a Qualified Rating Agency by Taiwan’s Financial Supervisory Commission and is recognized by the National Association of Insurance Commissioners as a Credit Rating Provider (CRP) in the U.S.